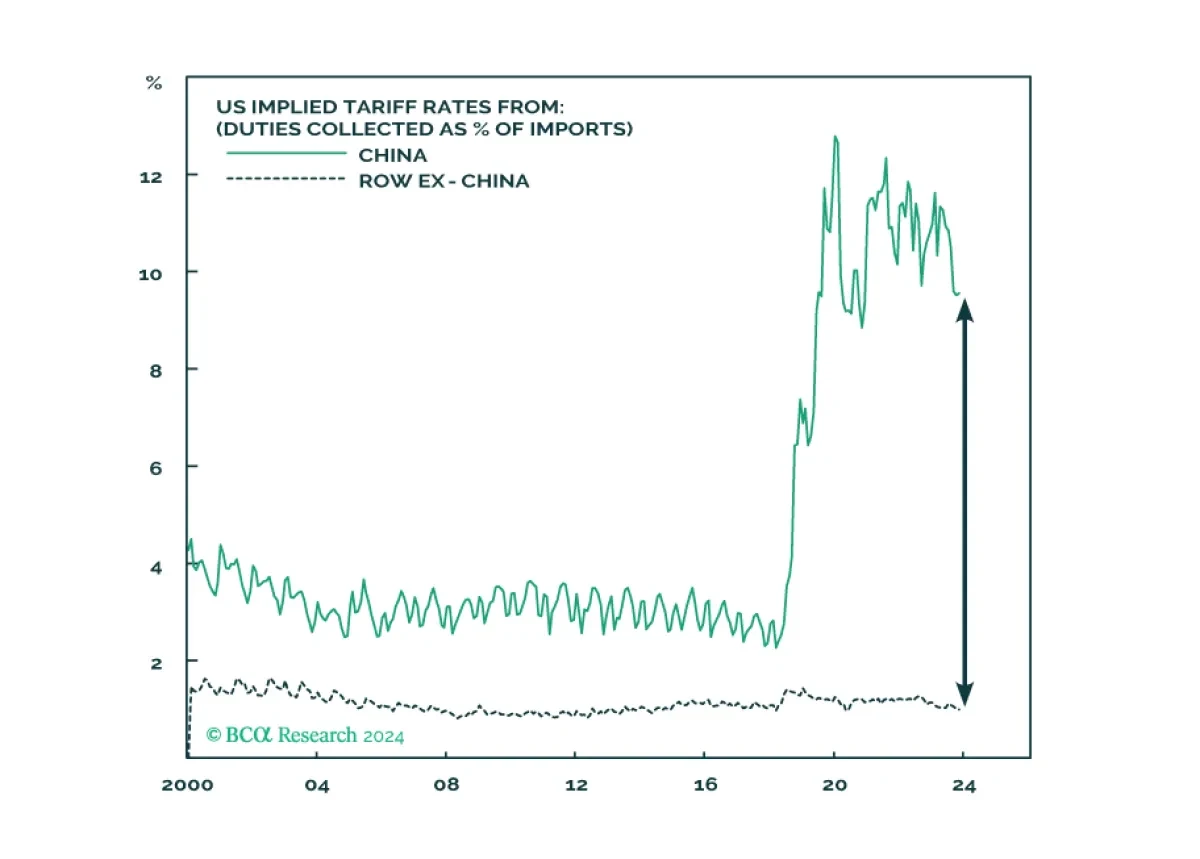
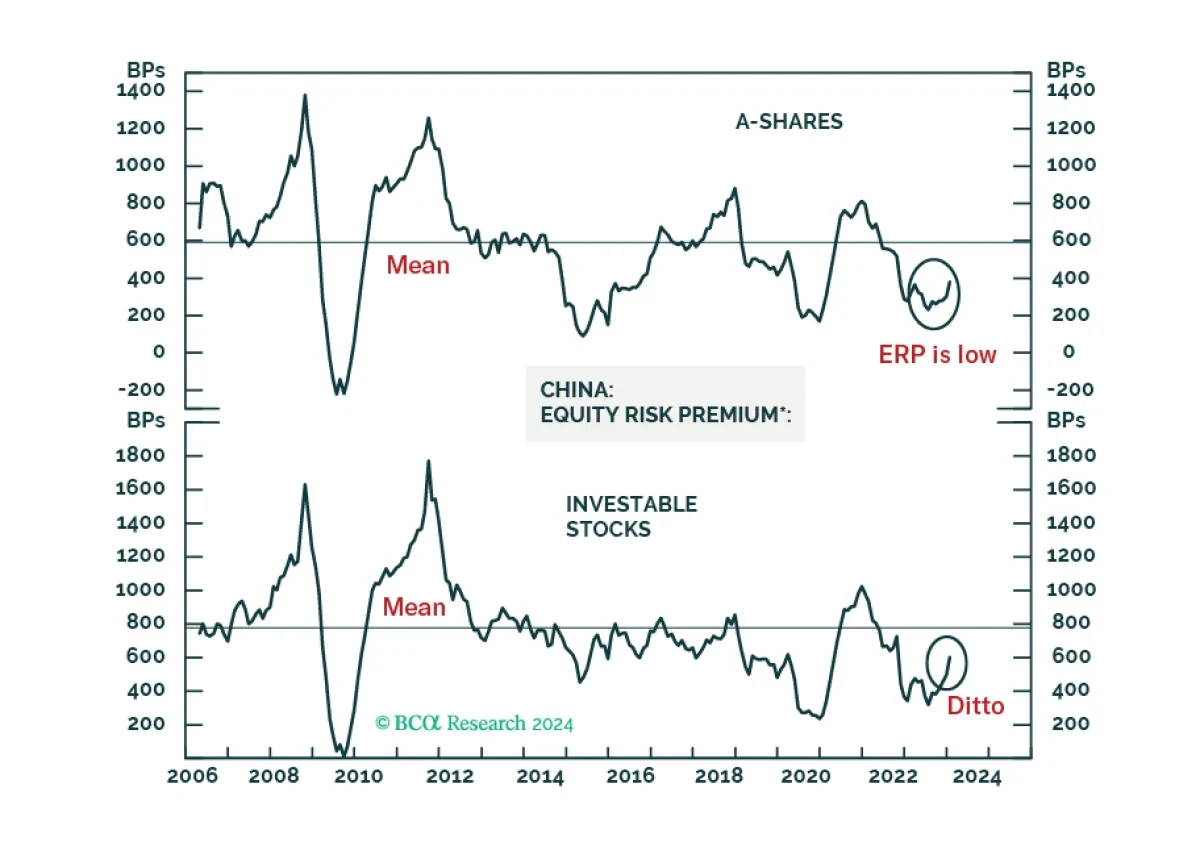
China will continue to suffer from a “triple crisis”. Though there could be a tactical bounce, cyclically we still recommend underweighting Chinese equities....
Chinese A-shares will probably begin forming a volatile bottom. The basis is that authorities will likely throw the kitchen sink at the onshore market in an attempt to stabilize share prices. The same is not true for offshore listed stocks. Hong Kong-traded Chinese share prices will likely continue ...
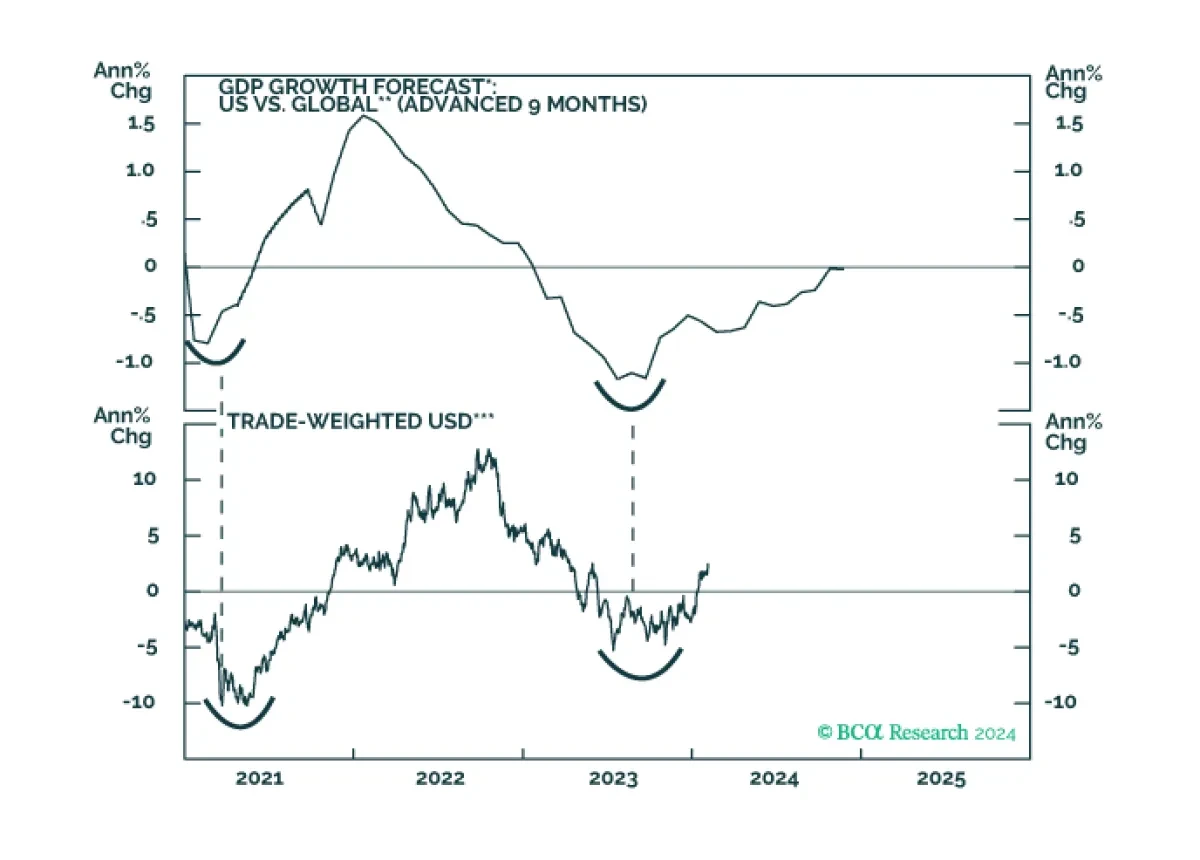
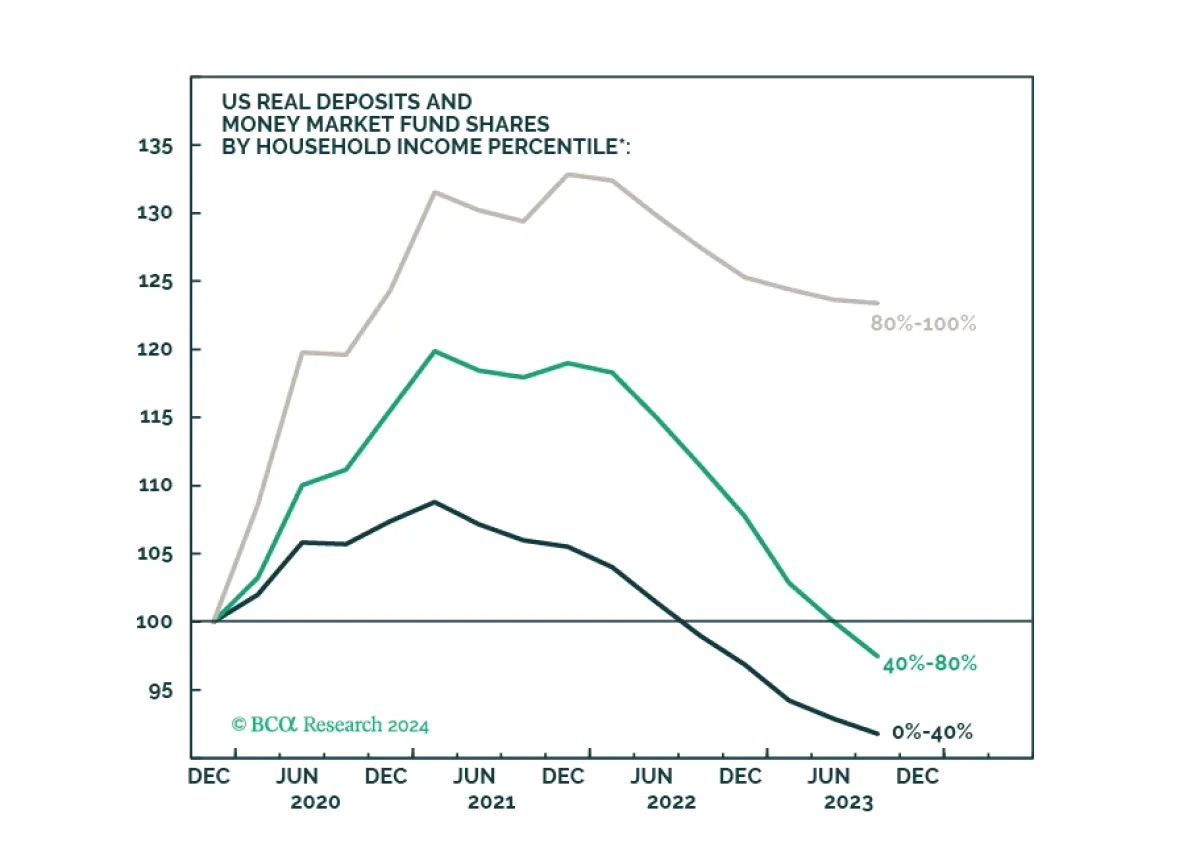
Easier financial conditions, rising home prices, rebounding consumer sentiment, and a stabilization in manufacturing activity all augur well for near-term US growth prospects. An unsustainably low savings rate is a key risk to the US economic outlook. Our revised forecast is centered on a recession ...
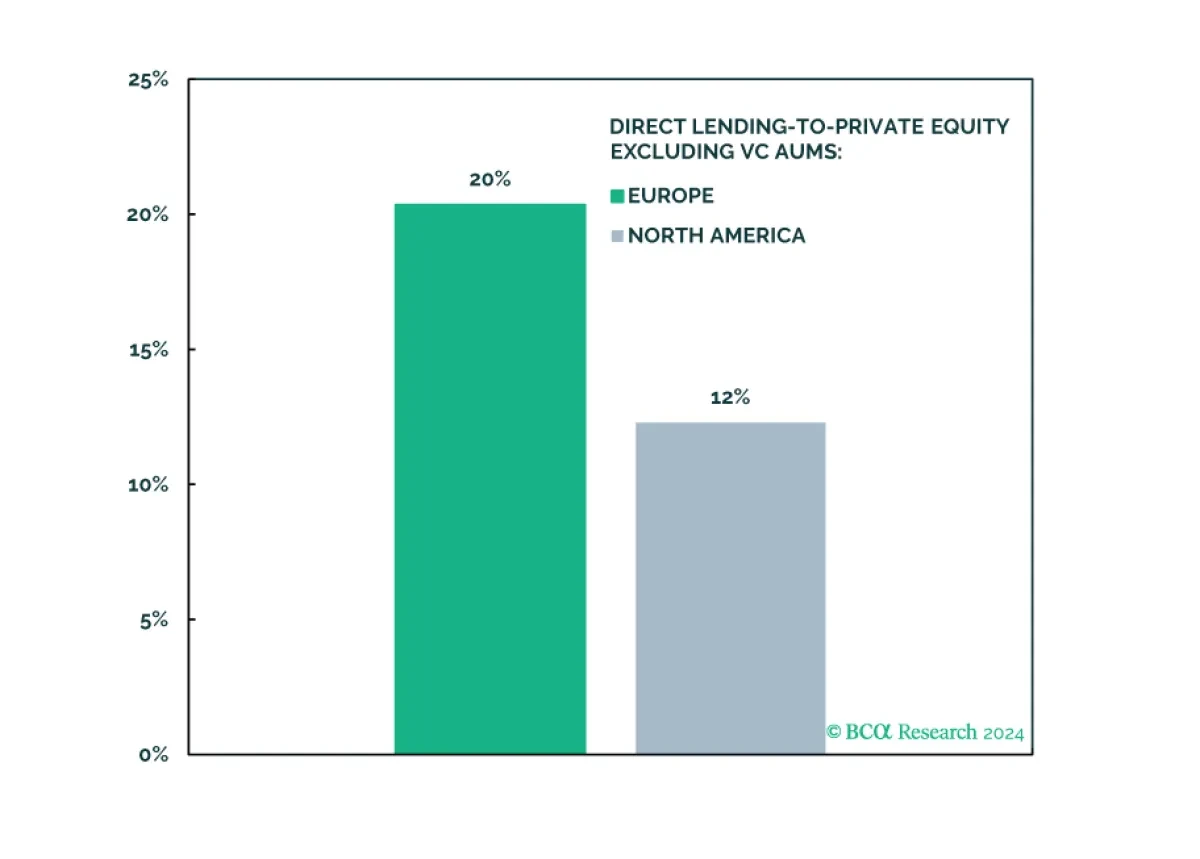
We are upgrading Europe Private Equity, predominantly driven by Buyouts, from underweight to neutral. Our outlook towards Global Buyouts is improving, with Europe benefiting from enhanced credit availability and an earlier recession. Non-domestic investors may also be advantaged by an appreciation i...
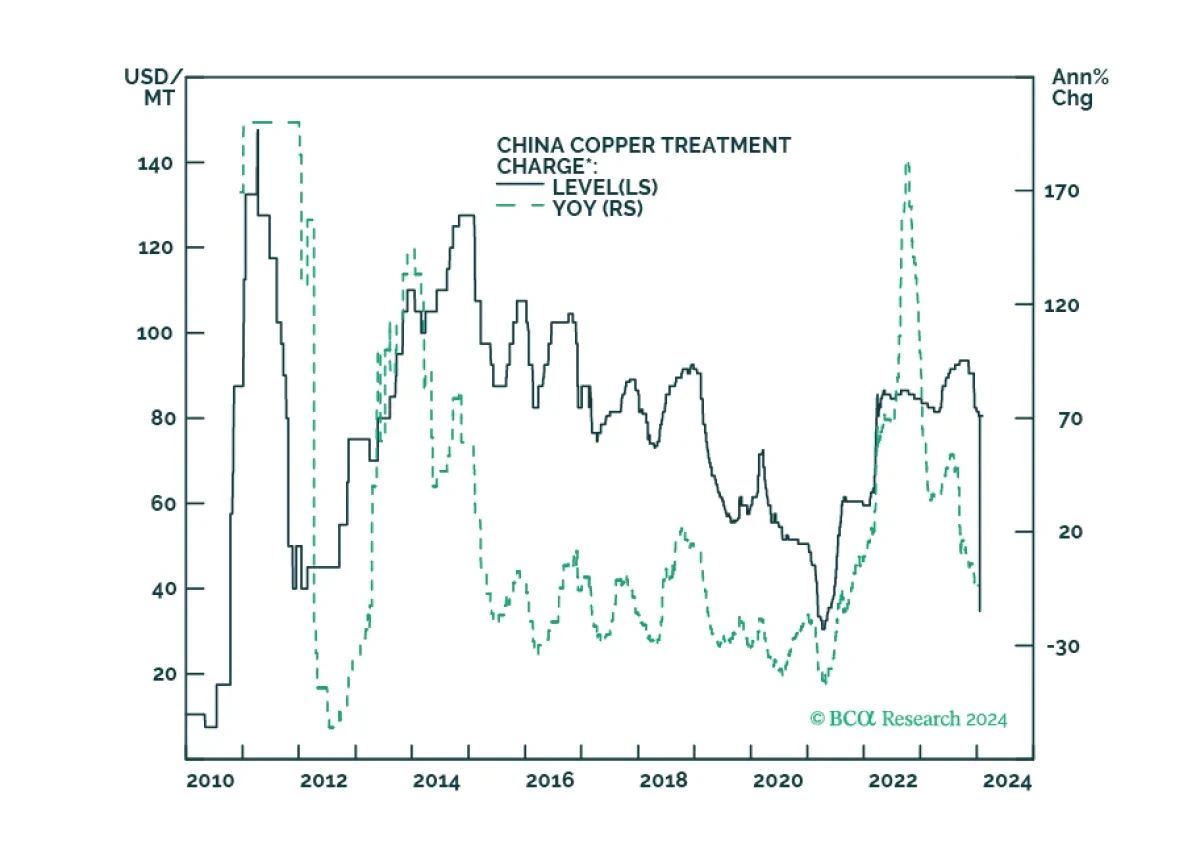
Supply and demand shocks in markets critical to the renewable-energy and defense industries will continue to play havoc with prices, which will negatively impact capex. In the short run, this benefits China given its already-dominant position in these markets. Longer term, investors already are prov...
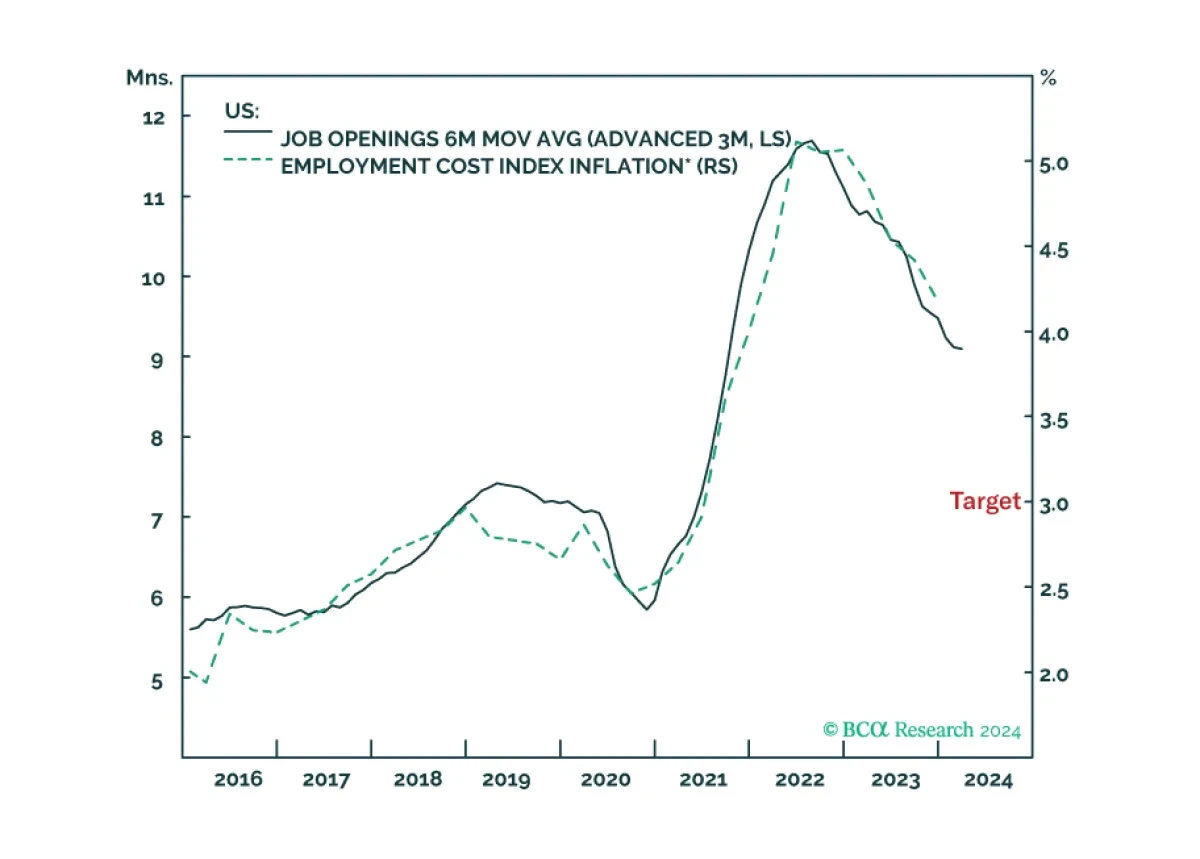
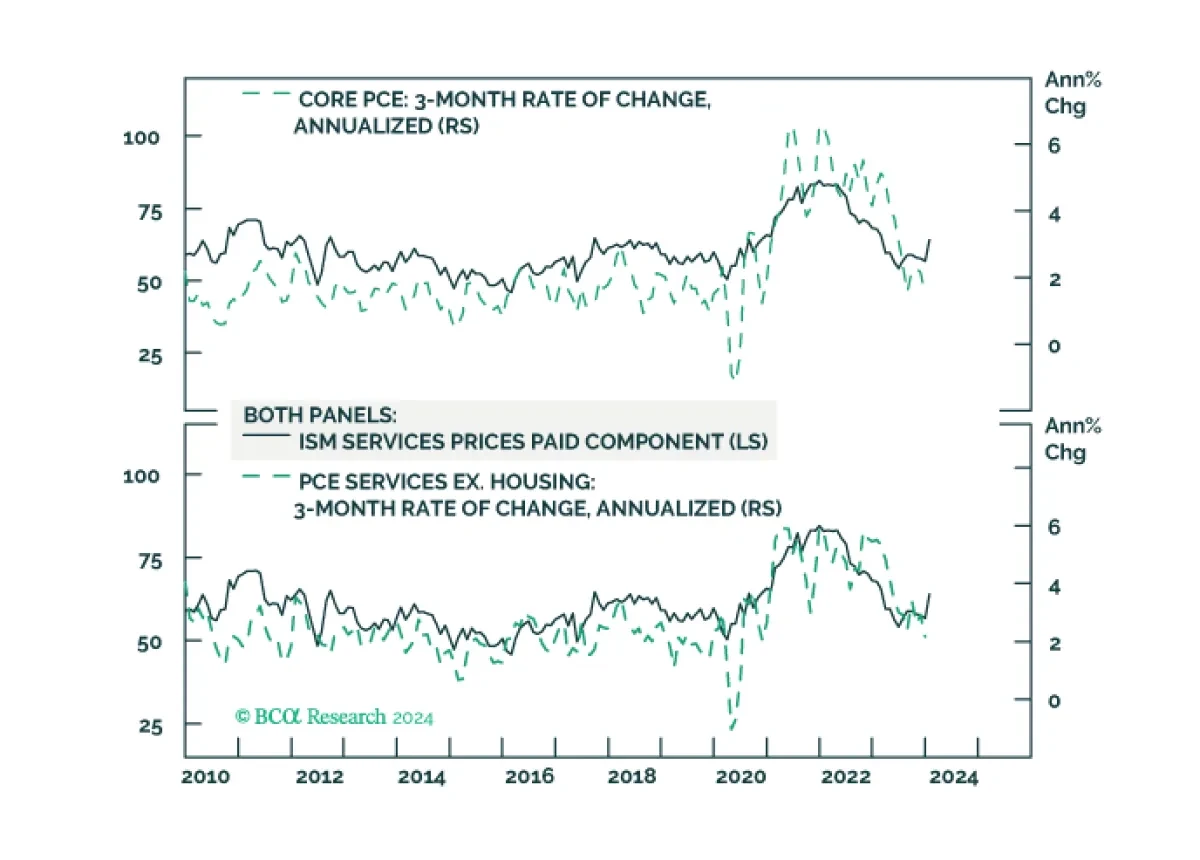
The disinflation to date has been benign because it has come almost entirely from improving supply. But the supply-side tailwind has exhausted, so the last mile of the journey to 2 percent inflation will be the hardest, especially in the US and the UK. We discuss the investment implications. Plus, w...
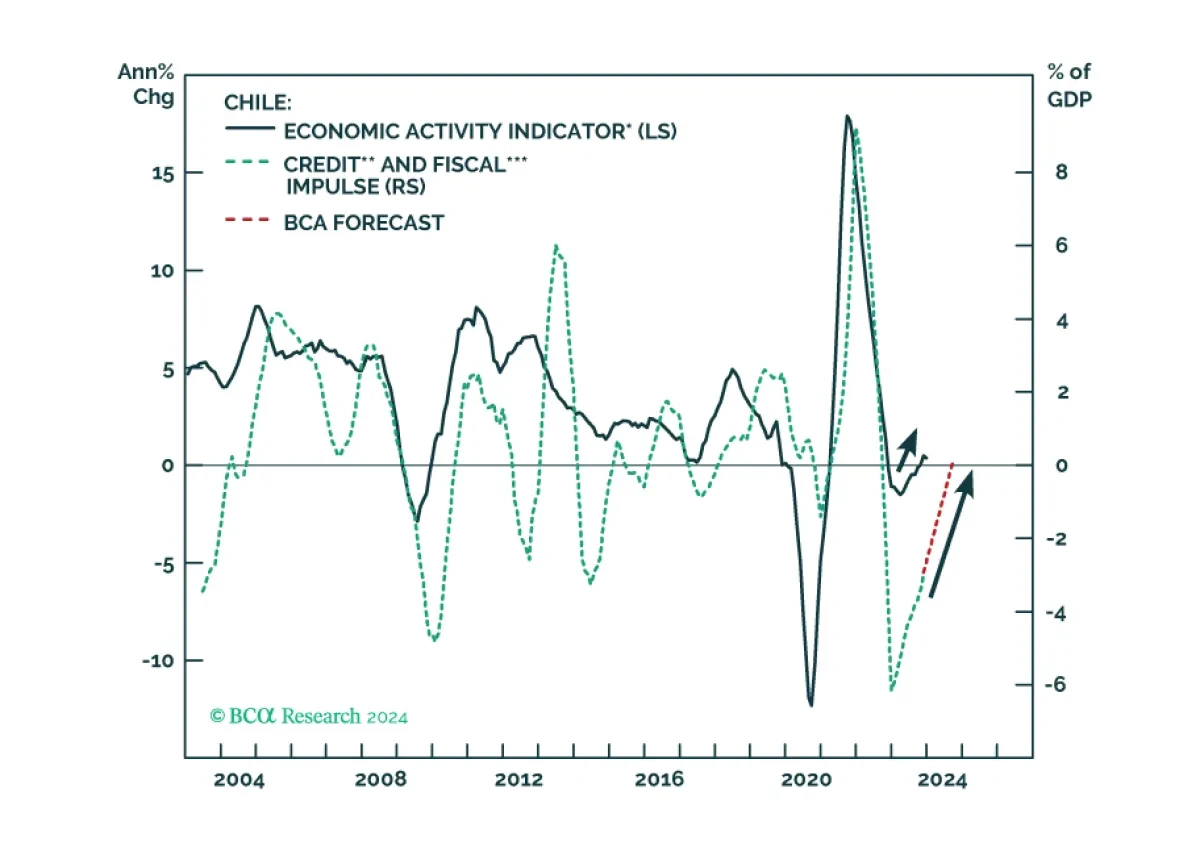
The stars have aligned for a major outperformance of Chilean stocks versus the EM equity benchmark. Plummeting inflation in Chile will push monetary authorities to continue their aggressive rate cuts, engineering a quick economic recovery this year. We maintain our overweight stance on Chilean stock...
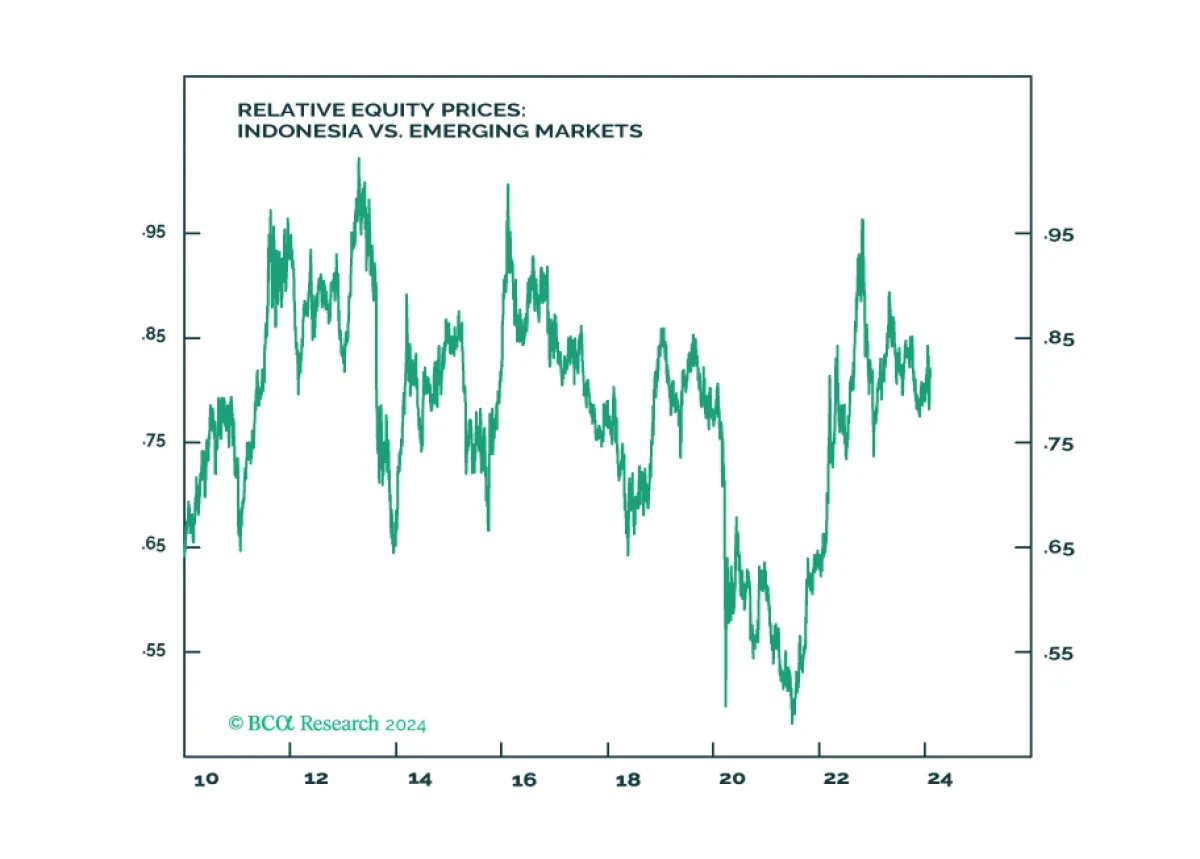
Indonesia will not revert to dictatorship. Yet the guardrails against authoritarianism are also constraining the actions of the next government in tackling near term domestic and regional challenges. For long-term positioning, use potential selloff from a “dictatorship scare” to build position as st...